What is a national audit institution?
Governments raise revenue, borrow money and spend public funds through many departments and programs. A national audit institution examines aspects of that financial activity and reports what it finds. Often called a supreme audit institution, it may take the form of an auditor general’s office, a court of audit or another public body. Its legal authority and relationship to the legislature vary by country.
An audit institution is not the same as the government department that keeps the accounts. Its role is to provide an examination separate from day-to-day management. That distinction matters: officials responsible for spending explain their decisions, while auditors assess records and practices against stated criteria. Audit reports can help legislators question officials and help the public see where financial controls are working or need attention.
What do auditors examine?
A financial audit considers whether financial statements fairly present the government’s finances under the accounting rules that apply. Auditors may test figures such as revenue, expenditure, assets and liabilities. They also consider the systems used to produce those figures. The resulting opinion addresses the statements as a whole; it does not certify that every individual transaction is correct.
Other audits ask different questions. A compliance audit examines whether spending and financial decisions followed applicable laws, budget authorizations or administrative rules. A performance audit considers how a program uses resources and whether its management supports its stated objectives. Depending on its mandate, an institution may also examine particular agencies, public enterprises or funds. These categories can overlap, but their conclusions should be read in light of the question each audit set out to answer.
How does an audit proceed?
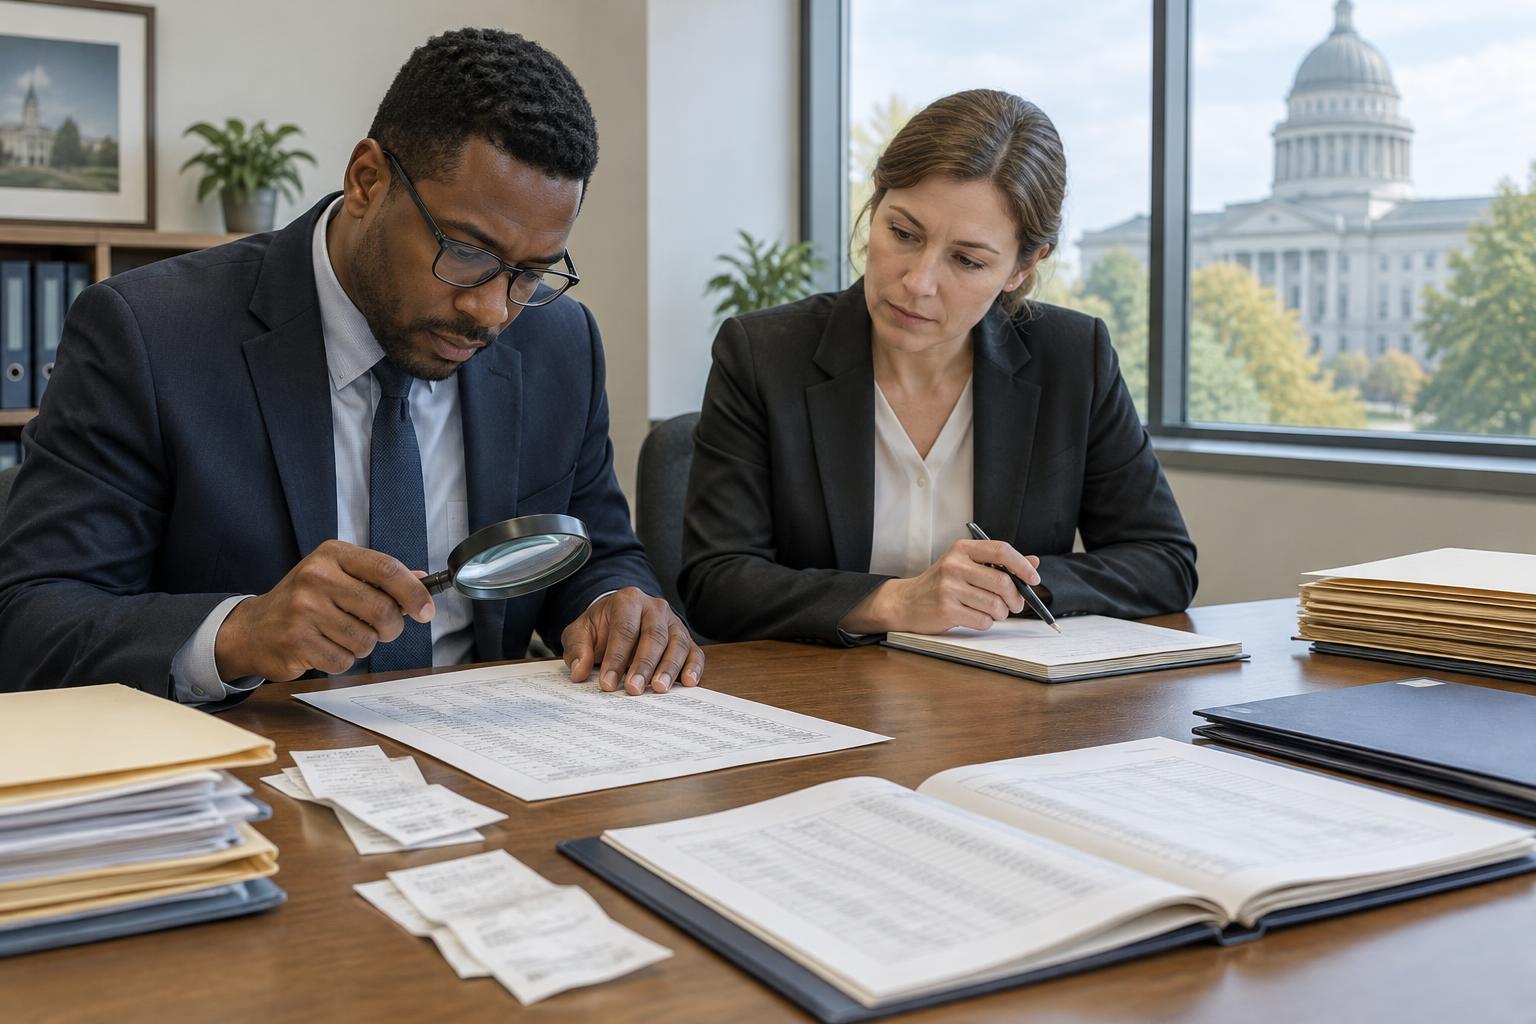
Auditors usually begin by defining the audit’s scope, criteria and main risks. They review documents such as budgets, contracts, payment records and financial statements. They may interview staff, observe procedures, compare records across systems or examine a sample of transactions. Sampling allows them to investigate a large body of activity without checking every item, but it also means their conclusions depend on the evidence gathered and the methods used.
Auditors then assess whether that evidence supports a finding. For example, missing approval records may show that a required control was not documented. They do not, by themselves, show that money was stolen. Audit teams generally give the audited body an opportunity to respond to draft findings or correct factual errors before publication. The final report may include the institution’s conclusion, the audited body’s response and recommendations for improvement.
Why independence and access matter
An audit institution needs enough distance from the bodies it examines to report uncomfortable findings. Rules governing appointments, removal, funding and publication can affect that independence. So can auditors’ practical ability to obtain records and speak with relevant staff. Formal protections do not remove every pressure, but they can make it harder for audited officials to control what is examined or reported.
Independence does not mean that auditors set government policy. Elected officials and administrators generally decide public priorities within their legal powers. Auditors can examine whether funds were accounted for, whether rules were followed and, where authorized, how effectively a program was managed. They may identify trade-offs or weaknesses without deciding which political goal a country ought to pursue.
How to read an audit report
Start with the report’s scope: which organization, period and activity did it cover? Next, look for the criteria and the kind of conclusion offered. A qualified opinion on financial statements, a compliance finding and a performance recommendation mean different things. Check whether a reported problem concerns an isolated transaction, a recurring control weakness or a limitation on the evidence auditors could obtain.
Finally, distinguish a finding from its resolution. Audit institutions can recommend changes and bring problems to public attention, but another body may be responsible for implementing recommendations, investigating suspected misconduct or changing a law. Follow-up reports can show whether an agency acted. An audit is most useful when readers treat it as a structured account of evidence and limits, rather than as a simple verdict on an entire government.